Behavioral Economics in Collections: Using Psychology to Drive Repayments
Borrowers are not spreadsheets. Small nudges in timing, framing, and choice design routinely outperform aggressive escalation. The science of getting to 'paid'.
The Repayment Decision Is Emotional Before It Is Financial
Collections strategy often assumes borrowers make rational calculations about money. Decades of behavioral economics say otherwise. People avoid stressful tasks, respond to social cues, anchor on round numbers, and treat future consequences as less real than present ones. Designing recovery journeys around how humans actually behave, rather than how we wish they did, consistently lifts resolution rates.
Nudges That Work on the Floor
These principles translate directly into collections practice:
- Timing: messages sent near salary dates or known paydays convert dramatically better than calendar-driven reminders.
- Framing: 'Protect your credit score' outperforms 'Avoid penalty' for the same payment. Loss framing around an asset the borrower values beats abstract threats.
- Choice architecture: offering two or three concrete payment options beats an open-ended 'pay what you can'.
- Commitment devices: a borrower who picks their own promise-to-pay date keeps it more often than one assigned a date.
- Fresh starts: restructuring framed as a 'new beginning' after a missed payment re-engages borrowers who had written the loan off mentally.
The Ethics Line
Nudging is not manipulation when the outcome benefits the borrower too: avoiding penalties, protecting their score, and closing stress-inducing debt. The line is crossed when design exploits confusion or fear. Regulators increasingly read collections scripts through exactly this lens, so the ethical approach is also the compliant one.
Building a Behavioral Playbook
Start small: A/B test message timing and framing on one portfolio segment, measure promise-keeping and payment rates, and scale what works. Over a few quarters, these experiments compound into a proprietary playbook, one reason modern collections teams employ journey designers alongside dialers.
See How FrenzoFinserv Puts This into Practice
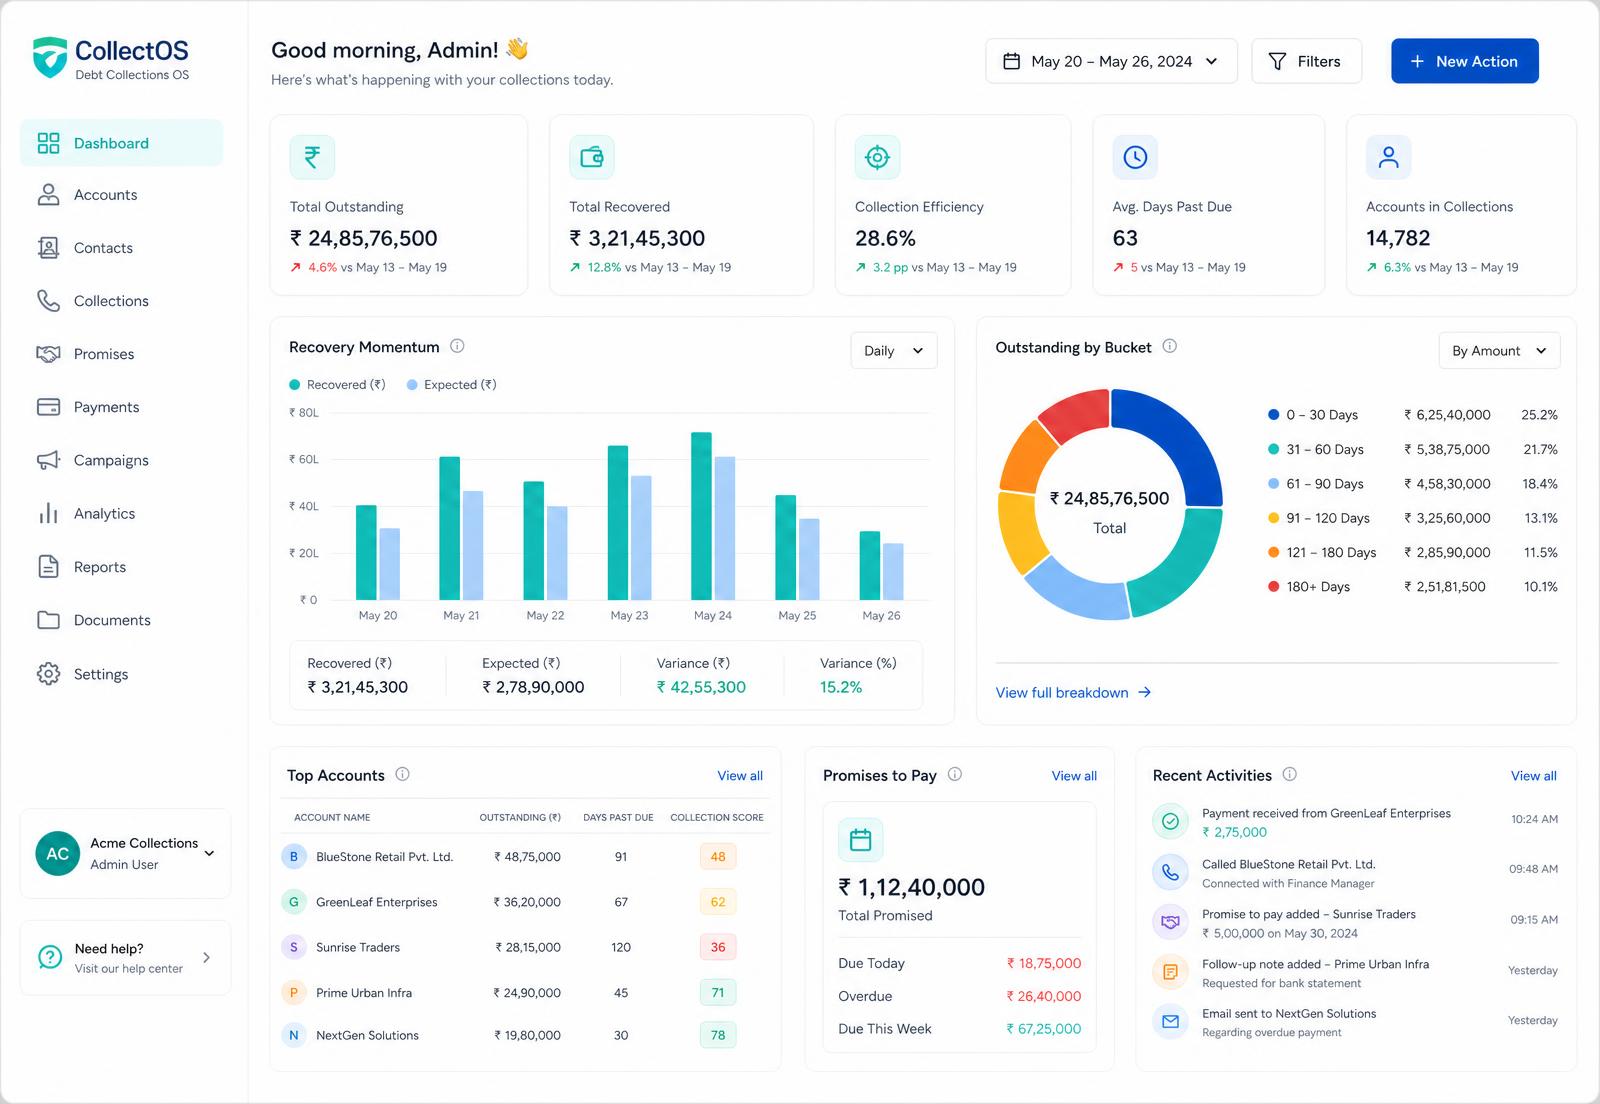
Our platform turns these ideas into daily operations for NBFCs, fintechs, and digital lenders across India.
Book a demo